Friday, July 16, 2010

tracking personal finances


Five Best Personal Money Management Sites


Web-based financial management tools have grown in sophistication to the point where many people manage their entire financial lives with online tools. Here's a look at five of the most popular personal money management sites.

Photo a mashup of images by Leonardini and Wilton.


Earlier this week we asked you to share your favorite personal money management site; now we're back to highlight the five most popular contenders.


Click on the screenshots below to take a closer look.


Buxfer (Basic: Free, Premium: From $2.79/month)


Many people are hesitant to use online banking services because of security concerns. Buxfer's compromise to provide ease of use while also assuring users and keeping things as controlled as they would like is to offer multiple methods for storing your credentials. You can manually synchronize your financial accounts with the site, you can store your passwords and login credentials locally using Google Gears, Firefox, or Safari, or you can use the Firebux Firefox extension—Firebux helps you automate the process of downloading financial data from your banking institutions and reviewing Buxfer data. If you'd like to skip the hassle of handling your own syncing, Buxfer offers automatic nightly syncing of your financial data, automatically logging into and pulling data from your various online money portals. Buxfer comes in three flavors: Basic (free), Plus ($2.79 per month), and Pro ($3.79 per month). All accounts include features like split bills, automatic tagging, and mobile access, but you'll pay a premium for unlimited budgets, bill reminders, and balance projections. You can try a live demo of Buxfer here.


Yodlee MoneyCenter (Free)


As many readers were quick to point out, Yodlee provides the guts to the user sites for hundreds of banking and financial services. Organizations like Mint, Thrive, and large banks like Chase use rebranded but Yodlee-powered interfaces. Yodlee users will often characterize Yodlee as similar to Mint, but without such a strong emphasis on flashy graphics. Instead it focuses more on analyzing your raw data—transaction descriptions, for example, are easier to search and more detailed. Yodlee can import data from thousands of institutions, help you generate a budget, automate your bill paying, and send out user-defined alerts. If you like the idea of a site like Mint but want more fine-grained control and the ability to manually tweak things when necessary, Yodlee is a solid alternative.


Mint (Free)


Mint has risen to prominence as a major player among web-based financial management tools by putting an extreme emphasis on user-friendliness and automation. The focus on automation is so strong, in fact, they only recently added the ability to add in any sort of manual transactions. By providing Mint with your various logins, you can track all your financial accounts in one place—checking, savings, credit cards, investments—and easily generate budgets and projections based off your data. Mint has won many people over, especially in the younger demographic, by being the first tool they've used to really get a good look at their money and where it's going.


ClearCheckbook (Basic: Free, Premium: $4/month)


ClearCheckbook is a web-based checking account ledger on steroids. You can track your spending, input your daily expenses from the web-interface or from your iPhone, Android, or Palm, and generate a budget with spending limits. Upgrading to a premium account gets you a custom report tool, custom transaction fields, future balance projection, and editing of the auto-suggest feature. Visit ClearCheckbook at the link above to check out the video tours of both the free and premium accounts—available at the bottom of the main page.


Mvelopes ($39.60/quarter)


Mvelopes is a robust web-based financial tool built on the old principle of budgeting with envelopes—each budget category gets an envelope with a set amount of money. Its focus on an old budgeting technique, however, doesn't mean you're stuck with dated tools. Mvelopes automatically pulls transaction data from hundreds of financial institutions, supports automatic bill payment, and helps you generate snapshots of your net worth as you adjust your budget and goals. Mvelopes is notable for being the only contender in the Hive without a free account option, a testament perhaps to how happy people are with the service that it made an appearance in the top five despite the lack of free-as-in-beer option.


Now that you've had a chance to look over the top five contenders for best personal money management sites, it's time to cast a vote for your favorite:


Have a favorite web-based tool that didn't get a nod or want to talk up your favorite a bit more? Let's hear it in the comments. Have an idea for the next Hive Five? Send us an email at tips@lifehacker.com with "Hive Five" in the subject line and we'll do our best to get your idea the attention it deserves.


Send an email to Jason Fitzpatrick, the author of this post, at jason@lifehacker.com.


Five Best Personal Money Management Sites


Web-based financial management tools have grown in sophistication to the point where many people manage their entire financial lives with online tools. Here's a look at five of the most popular personal money management sites.

Photo a mashup of images by Leonardini and Wilton.


Earlier this week we asked you to share your favorite personal money management site; now we're back to highlight the five most popular contenders.


Click on the screenshots below to take a closer look.


Buxfer (Basic: Free, Premium: From $2.79/month)


Many people are hesitant to use online banking services because of security concerns. Buxfer's compromise to provide ease of use while also assuring users and keeping things as controlled as they would like is to offer multiple methods for storing your credentials. You can manually synchronize your financial accounts with the site, you can store your passwords and login credentials locally using Google Gears, Firefox, or Safari, or you can use the Firebux Firefox extension—Firebux helps you automate the process of downloading financial data from your banking institutions and reviewing Buxfer data. If you'd like to skip the hassle of handling your own syncing, Buxfer offers automatic nightly syncing of your financial data, automatically logging into and pulling data from your various online money portals. Buxfer comes in three flavors: Basic (free), Plus ($2.79 per month), and Pro ($3.79 per month). All accounts include features like split bills, automatic tagging, and mobile access, but you'll pay a premium for unlimited budgets, bill reminders, and balance projections. You can try a live demo of Buxfer here.


Yodlee MoneyCenter (Free)


As many readers were quick to point out, Yodlee provides the guts to the user sites for hundreds of banking and financial services. Organizations like Mint, Thrive, and large banks like Chase use rebranded but Yodlee-powered interfaces. Yodlee users will often characterize Yodlee as similar to Mint, but without such a strong emphasis on flashy graphics. Instead it focuses more on analyzing your raw data—transaction descriptions, for example, are easier to search and more detailed. Yodlee can import data from thousands of institutions, help you generate a budget, automate your bill paying, and send out user-defined alerts. If you like the idea of a site like Mint but want more fine-grained control and the ability to manually tweak things when necessary, Yodlee is a solid alternative.


Mint (Free)


Mint has risen to prominence as a major player among web-based financial management tools by putting an extreme emphasis on user-friendliness and automation. The focus on automation is so strong, in fact, they only recently added the ability to add in any sort of manual transactions. By providing Mint with your various logins, you can track all your financial accounts in one place—checking, savings, credit cards, investments—and easily generate budgets and projections based off your data. Mint has won many people over, especially in the younger demographic, by being the first tool they've used to really get a good look at their money and where it's going.


ClearCheckbook (Basic: Free, Premium: $4/month)


ClearCheckbook is a web-based checking account ledger on steroids. You can track your spending, input your daily expenses from the web-interface or from your iPhone, Android, or Palm, and generate a budget with spending limits. Upgrading to a premium account gets you a custom report tool, custom transaction fields, future balance projection, and editing of the auto-suggest feature. Visit ClearCheckbook at the link above to check out the video tours of both the free and premium accounts—available at the bottom of the main page.


Mvelopes ($39.60/quarter)


Mvelopes is a robust web-based financial tool built on the old principle of budgeting with envelopes—each budget category gets an envelope with a set amount of money. Its focus on an old budgeting technique, however, doesn't mean you're stuck with dated tools. Mvelopes automatically pulls transaction data from hundreds of financial institutions, supports automatic bill payment, and helps you generate snapshots of your net worth as you adjust your budget and goals. Mvelopes is notable for being the only contender in the Hive without a free account option, a testament perhaps to how happy people are with the service that it made an appearance in the top five despite the lack of free-as-in-beer option.


Now that you've had a chance to look over the top five contenders for best personal money management sites, it's time to cast a vote for your favorite:


Have a favorite web-based tool that didn't get a nod or want to talk up your favorite a bit more? Let's hear it in the comments. Have an idea for the next Hive Five? Send us an email at tips@lifehacker.com with "Hive Five" in the subject line and we'll do our best to get your idea the attention it deserves.


Send an email to Jason Fitzpatrick, the author of this post, at jason@lifehacker.com.


mike fuljenz mike fuljenz mike fuljenz mike fuljenz mike fuljenz mike fuljenz

Stabroek <b>News</b> - Deal signed in Shanghai for Amaila

Good News but: 1) strange that the Minister went to Parliament to give info.! I mean, as he said, the Pres. is in China. So one figure this was a staged reporting exercise OR, Norway demanded this report to PArliament ...

Google Bows to Criticism, Changes Google <b>News</b> Design

Just two weeks after launching a new version of its Google News site with additional personalization features, the web giant has changed the design in response to complaints from users, giving them the option to revert to a design more ...

Small Business <b>News</b>: The Better Business Owner | Small Business Trends

Who is the better business owner? Could it be you? Today we realize that it is not so much money or the right connections that make a business succeed in the.

2009_10_02_0009 by Vikram Chadaga


2009_10_02_0009 by Vikram Chadaga


Thursday, July 15, 2010

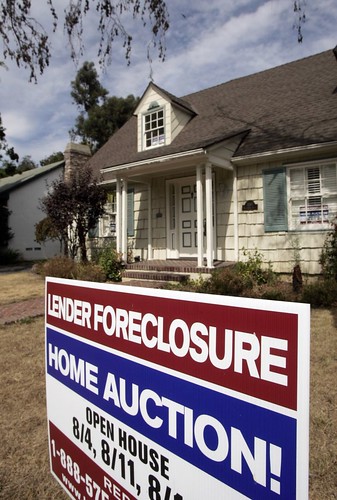
foreclosure sales


  • Recent Posts


    • Goldman Sachs Settles With SEC For Mere $550 Million, Shares Rise

    • Google Earnings Trend Becomes That of Disappointment (GOOG)

    • European Auto Sales Continue to Slide

    • Google Earnings Set to Move Peers, a Full Preview (GOOG, BIDU, YHOO, MSFT, AAPL)

    • Chinese Banking Woes

    • Today’s Best Market Rumors (7/15/2010)

    • Top Day Trader Alerts (AMZN, ARNA, BP, NTY, OREX, VRNM, VVUS)

    • The Twitter-24/7 Wall St. Stock Market Report 7.15.2010 The Wisdom Of Crowds

    • Top Analyst Upgrades & Downgrades (BZH, BP, CIEN, GLW, EXPE, FFIV, BEN, JNS, JNPR, PMCS, PCLN, SPWRA, TROW)

    • JPMorgan Chase (JPM) Beats

    • More Real Estate Trouble: Foreclosures Hit 1.65 Million in First Half

    • The Question Emerges Again: What If The Well Can’t Be Capped

    • Economic Confidence Slips As Problem Becomes Center Of Attention

    • Global PC Sales: Dell Fights Back

    • China And The US, Economies Move In Different Directions

    • Media Digest 7/15/2010 Reuters, WSJ, NYTimes, FT, Bloomberg

    • Market Recovery: The Return of M&A in Tech and Telecom (ADCT, TEL, HPQ, ORCL, CIEN, Q, CTL, BRCD, CBB, CVLT, DELL, JDSU, LEAP, PCS, WFR, NOVL, PGI, RSH, TLAB, TDC, OVTI, SYNA)

    • Shippers Face More Woes on Over-capacity (DRYS, DSX, GNK, AMKBF)

    • FOMC Minutes: Years of Spotty Economics

    • More Data Against A Double-Dip Recession

    • Home Health Care Providers Under Scrutiny (LHCG, AMED, AFAM, GTIV)

    • Northrop Closure Signals Troubled Times For Defense (NOC)

    • Reality Sets in at Playboy (PLA)

    • Top Day Trader Alerts (BP, CTIC, GTIV, INTC, AMD, ASML, NVDA, SMH, JTX, LHCG, VVUS)

    • Top Analyst Upgrades & Downgrades (ADCT, ALL, AMSC, BSX, CSIQ, ENOC, ITRI, JASO, KBH, LIFE, MDT, PLD, RYL, SHW, TSL, VVUS, YGE)

    • Oil Keeps Gushing, As US Dithers

    • GE’s Immelt–A Strategic Retreat

    • 4.7 Workers For Every Job

    • The Trade Gap And The Yuan, Gone And Forgotten

    • The American Ecomomy Can Heal Itself, If Only The Economy Would Help


  • Archives


    • July 2010

    • June 2010

    • May 2010

    • April 2010

    • March 2010

    • February 2010

    • January 2010

    • December 2009

    • November 2009

    • October 2009

    • September 2009

    • August 2009


This week's shocking existing home sales and new home sales data are a reminder that government support for the housing market is starting to unwind. The bad data we saw this week was just the beginning of a 'hangover' from our recent housing stimulus binge:


Goldman's Jan Hatzius:


The effect of federal mortgage modification programs has also started to wane. Data reported from the Treasury this week indicate that the number of canceled modifications in the Home Affordable Modification Program (HAMP) jumped significantly, while the rate of new modifications has declined to a fraction of the previous pace. Most of these loans have not yet entered foreclosure, and it appears that many will enter non-federal modifications. That said, the effect of this program is nevertheless starting to reverse, from one that absorbed would-be distressed supply from the market, to one that will at some point add it back.


But we still have ultra-low mortgage rates... (In fact, the lowest mortgage rates ever in recorded history)


The third source of policy support for the housing market-low mortgage rates-remains intact, however. While the conforming spread has risen by roughly 30bps from its low point at the end of the Fed's MBS purchases in March, it is still significantly below normal levels. Since most of the effect of the Fed's purchases appears to come from the stock of MBS holdings, we don't expect this source of support to fade soon. However, GSE reform discussions that get underway later this year and become more intense early in 2011 could present a new risk to this last source of temporary policy support.


Still, as government support fades, Goldman is forecasting falling housing prices out to 2012:


Last year, we estimated that federal housing policies-the homebuyer tax credit, mortgage modification programs, and the Fed's MBS purchases-boosted house prices by about 5%, with the implication that the fading of these policies would lead to renewed price declines in 2010. Earlier this month we updated our house price forecast; we expect a 3% decline in the Case-Shiller 20-city index this year and another 1% in 2011 (see Jari Stehn, "House Prices Have Not Bottomed Yet", US Economics Analyst 10/22, June 4, 2010). Reports this week back up the notion that the first two of these supports have begun to fade, though the third remains largely intact:


The homebuyer tax credit hangover is happening:


Collapsing mortgage applications presaging collapsing existing home sales...


Collapsing new home sales...


Basically, don't be surprised if home prices go nowhere, at best, for a long time.


(Via Goldman Sachs, The Unwinding Of Federal Housing Stimulus Is Underway, Jan Hatzius, 23 June 2010)


synopsis


BREAKING <b>NEWS</b>: Joseph Lacob and Peter Guber outbid Larry Ellison <b>...</b>

The word is that the new owner of the Golden State Warriors is NOT Larry Ellison, but Joseph Lacob and Peter Guber.

Lebanon arrests another telecom worker for spying - Arab <b>News</b>

At no time will Arab News attempt to alter the core meaning of a comment. 3. Reject the message, edit the message when the moderators judge it to be a personal attack, defamatory (or potentially defamatory), abusive, incite hatred or ...

FOX <b>News</b> Pushes Unsubstantiated Threat of Lesbian Prison Gang <b>...</b>

Maybe Jack Tapper and Ruth Marcus will come to their rescue again because I imagine Tapper will just say that FOX News was getting their info from one uncorroborated source inside the prison walls and it's a very dangerous place to do ...


Wednesday, July 14, 2010

why internet marketing


By Tess Alps: Why is TV-dissing such a big part of internet orthodoxy? Clay Shirky has been out promoting his new book, Cognitive Surplus, which states that internet activity is displacing TV among the young and that this is a good thing. There have been newspaper reviews like this and yesterday he was interviewed on Radio 4’s Today programme.


To be fair to Shirky, he doesn’t say that all TV is “bad”, but he believes that being online is better – connecting, creating, sharing. I would have to be a philistine not to recognise the many positive benefits that the internet has brought us, and I share Shirky’s idealistic hope that it will promote democracy, knowledge, peace, love etc.


My problems with his book are three-fold: I dispute some of his facts, some of the distinctions that he draws and some of the science that he employs.


Facts first: is TV viewing declininTo be fair to Shirky, he doesn’t say that all TV is “bad”, but he believes that being online is better – connecting, creating, sharing. I would have to be a philistine not to recognise the many positive benefits that the internet has brought us, and I share Shirky’s idealistic hope that it will promote democracy, knowledge, peace, love etc.


My problems with his book are three-fold: I dispute some of his facts, some of the distinctions that he draws and some of the science that he employs.g for the first time ever among the young? Not in the UK or Europe, and TV catch-up services online are extra. TV viewing is booming in developing markets. Anyone who has watched the World Cup coverage will have been moved to see young African children joyfully watching their first TV football match.


Secondly, to position the internet as an alternative to TV is meaningless – and I don’t say that lightly, because Clay Shirky is clearly a very intelligent person. The internet is a vast and transformational technology, but it is not a homogenous medium.


Many human activities that once took place offline can now be conducted online, including watching TV. A growing percentage of young people’s time online is spent watching TV and video – and then talking about it, as a quick glance at Twitter will prove. Sadly, there is about a 1:99 ratio between people who create things online and those who just consume them, much as in the real world; and TV inspires online creativity.


Finally, a bit of science. The word “passive” is often used to denigrate TV viewing. There might be less physical movement than twitching with a mouse but the brain is deeply engaged watching TV. The brain is a complex organism; the very title of Shirky’s book indicates he overvalues rational and cognitive processes over emotional intelligence and education; action over feelings.


We have just finished some neuroscientific research looking at the difference in the brain activity between watching TV and browsing websites (largely text based) and the differences are marked. TV is much stronger in areas such as emotion and long-term memory encoding and web browsing is stronger for visual attention. So they are different – but complementary.


Watching TV is a mostly shared experience; the real-life conversations within families that TV provokes are enormously valuable. Entertaining people and promoting happiness is a noble pursuit; TV is the master. But we should also recognise TV’s vast role as an informer, educator and promoter of democracy every bit as important as the internet.


Most of the time, the ease that the internet brings to human endeavour is brilliant, but I can think of areas where it has casualised and arguably cheapened some things. What’s the exchange rate between an online click on a petition and a Jarrow marcher? Birthday wishes on Facebook take a mere two seconds.


I could reverse what Shirky does and make unfair comparisons between the best of TV and the worst of the internet: is it better to watch Survival and Dispatches or to play to World of Warcraft and poke a friend? But I’d rather value both these massive cultural treasures for all the good they can do, separately and together.


Tess Alps is chief executive of Thinkbox, the marketing body for UK commercial TV


Today we acknowledge and celebrate the revolution of media becoming social. A day that honors the technological and societal advancements that have allowed us to have a dialogue, to connect and to engage not only the creators of media, but perhaps more importantly, one another.

It’s a day to celebrate the changes in media that have empowered us to stay connected to information in real time, the tools that have enabled us to communicate from miles apart, and the platforms that have given a voice to the voiceless and victims of protest injustice. It’s a revolution worth celebrating. Today, we celebrate Social Media Day and we hope you’ll join us.

So how do you participate? Being social, of course. You can do this online by tracking the social updates in various ways as listed below, or you can make some connections offline by attending an event near you. There are more than 600+ meetups in 93 countries today with thousands of attendees. As far as we know, there is no official holiday dedicated to social media. We think it deserves a day of it’s own, and what better way to celebrate than to connect with your local social media community?

There are lot’s creative events planned from panels, to charity fundraisers and even sporting tournaments. Below is a message from our very own Pete Cashmore explaining the idea, reasons for and goals behind Social Media Day:

A Message From Mashable’s Founder and CEO Pete Cashmore

So what’s next? As Pete mentions, we want this to be a launching point for you to build a lasting relationship with your social media community by continuing to host Monthly Mashable Meetups using our Meetup Everywhere page, or more frequently if you think it works better for your community.

Perhaps today’s local meetup was a place for you to network, but now you can take it one step further by organizing panels, demos and more — or maybe you can just keep it simple with monthly social networking meetups. The point is, let’s keep this social community connected, online and off. And next year, watch for the second annual Social Media Day, as we hope to continue to build on this celebration. The next date of the meetups will be July 27th, class='blippr-nobr'>Mashable’sclass="blippr-nobr">Mashable 5th birthday. Stay tuned and stay social!

How To Participate in Social Media Day

  • Meetup Everywhere Mashable: Sign up to attend an event on the Meetup Everywhere Mashable.
  • Watch the live streams worldwide: We’ll be updating throughout the day.
  • Tweet: Use the #smday hashtag on class='blippr-nobr'>Twitterclass="blippr-nobr">Twitter. With so many participating, we should be a trending topic on Twitter on June 30. Also, we’ll soon be announcing a prize for those that tweet or post to class='blippr-nobr'>Facebookclass="blippr-nobr">Facebook.
  • Add the Social Media Day Twitter theme from TweetyGotBack to your account in support of the day.
  • Follow @mashSMday: Follow @mashSMday on Twitter for updates and developments on the celebration.
  • Comment via Facebook: Go to Smday.com and leave a comment either promoting your meetup or tell us what you’re doing for your event.
  • Upload to class='blippr-nobr'>Flickrclass="blippr-nobr">Flickr: Upload photos to Flickr and tag them with #smday.

Winner of Sony Dash Giveaway

Last week we announced a Sony Dash giveaway that would be awarded to an attendee of a Social Media Day meetup in the U.S. and had fanned us on Facebook. The winner is Heather Spring, an Internet Marketing Manager at Accenture in Chicago, and is attending the Wheaton, Illinois meetup today with a crowd of about 40. Spring, who prior to entering the web world worked as a nuclear engineer, heard about the local meetup through the Mashable e-mail newsletter. She thinks meetups are a great way to socialize in real life with other social media professionals.

“Hopefully we can have conversations longer than 140-character tweets,” Spring said. Why is social media day worth celebrating? She said because “social media has become such a force that allows anyone to be heard – no matter where they are or who they are or what they have to say. And there’s always someone willing to listen.” Congrats to Heather on the prize!

Top 10 Meetups (Based on Attendance)

1. New York, NY/> 2. Sao Paulo, Brazil/> 3. Barcelona, Spain/> 4. Santa Ana, CA/> 5. Antwerp, Belgium/> 6. Buenos Aires, Argentina/> 7. Atlanta, GA/> 8. Boston, MA/> 9. Philadelphia, PA/> 9. Chicago, IL/> 10. San Francisco, CA

Social Media Day Tweets

/>

See the Closest Meetup to Your City

We’d also love to hear what you’re doing for Social Media Day in the comments below or in the Facebook comments section on Smday.com.

For more Social Media coverage:

    class="f-el">class="cov-twit">Follow Mashable Social Mediaclass="s-el">class="cov-rss">Subscribe to the Social Media channelclass="f-el">class="cov-fb">Become a Fan on Facebookclass="s-el">class="cov-apple">Download our free apps for iPhone and iPad

online stock trading online stock trading

New Harry Potter supports Kinect Xbox 360 <b>News</b> - Page 1 <b>...</b>

Read our Xbox 360 news of New Harry Potter supports Kinect.

Apple exec Scott Forstall joins Twitter | iLounge <b>News</b>

iLounge news discussing the Apple exec Scott Forstall joins Twitter. Find more Apple news from leading independent iPod, iPhone, and iPad site.

New Fox <b>News</b> App Shows Big Media Investing In Google&#39;s Android

As far as we can tell, neither CNN nor MSNBC, FNC's cable news rivals, have created Android apps. But third party apps appear to exist for both networks. (We have an email out to Google to confirm which news outlets have developed their ...


Saturday, July 10, 2010

why internet marketing


By Tess Alps: Why is TV-dissing such a big part of internet orthodoxy? Clay Shirky has been out promoting his new book, Cognitive Surplus, which states that internet activity is displacing TV among the young and that this is a good thing. There have been newspaper reviews like this and yesterday he was interviewed on Radio 4’s Today programme.


To be fair to Shirky, he doesn’t say that all TV is “bad”, but he believes that being online is better – connecting, creating, sharing. I would have to be a philistine not to recognise the many positive benefits that the internet has brought us, and I share Shirky’s idealistic hope that it will promote democracy, knowledge, peace, love etc.


My problems with his book are three-fold: I dispute some of his facts, some of the distinctions that he draws and some of the science that he employs.


Facts first: is TV viewing declininTo be fair to Shirky, he doesn’t say that all TV is “bad”, but he believes that being online is better – connecting, creating, sharing. I would have to be a philistine not to recognise the many positive benefits that the internet has brought us, and I share Shirky’s idealistic hope that it will promote democracy, knowledge, peace, love etc.


My problems with his book are three-fold: I dispute some of his facts, some of the distinctions that he draws and some of the science that he employs.g for the first time ever among the young? Not in the UK or Europe, and TV catch-up services online are extra. TV viewing is booming in developing markets. Anyone who has watched the World Cup coverage will have been moved to see young African children joyfully watching their first TV football match.


Secondly, to position the internet as an alternative to TV is meaningless – and I don’t say that lightly, because Clay Shirky is clearly a very intelligent person. The internet is a vast and transformational technology, but it is not a homogenous medium.


Many human activities that once took place offline can now be conducted online, including watching TV. A growing percentage of young people’s time online is spent watching TV and video – and then talking about it, as a quick glance at Twitter will prove. Sadly, there is about a 1:99 ratio between people who create things online and those who just consume them, much as in the real world; and TV inspires online creativity.


Finally, a bit of science. The word “passive” is often used to denigrate TV viewing. There might be less physical movement than twitching with a mouse but the brain is deeply engaged watching TV. The brain is a complex organism; the very title of Shirky’s book indicates he overvalues rational and cognitive processes over emotional intelligence and education; action over feelings.


We have just finished some neuroscientific research looking at the difference in the brain activity between watching TV and browsing websites (largely text based) and the differences are marked. TV is much stronger in areas such as emotion and long-term memory encoding and web browsing is stronger for visual attention. So they are different – but complementary.


Watching TV is a mostly shared experience; the real-life conversations within families that TV provokes are enormously valuable. Entertaining people and promoting happiness is a noble pursuit; TV is the master. But we should also recognise TV’s vast role as an informer, educator and promoter of democracy every bit as important as the internet.


Most of the time, the ease that the internet brings to human endeavour is brilliant, but I can think of areas where it has casualised and arguably cheapened some things. What’s the exchange rate between an online click on a petition and a Jarrow marcher? Birthday wishes on Facebook take a mere two seconds.


I could reverse what Shirky does and make unfair comparisons between the best of TV and the worst of the internet: is it better to watch Survival and Dispatches or to play to World of Warcraft and poke a friend? But I’d rather value both these massive cultural treasures for all the good they can do, separately and together.


Tess Alps is chief executive of Thinkbox, the marketing body for UK commercial TV


That lame Hotmail tagline is why I convinced my now wife to get a Gmail account a couple years ago. I told her "whenever you send someone an e-mail, you're advertising for Hotmail." She was starting to sell custom clothing on-line, to which I added "do you really want to spam your customers with Hotmail ads every time you send an e-mail." It wasn't long before her Hotmail became a legacy inbox for spam and mailing lists and Gmail is her primary e-mail platform. It also helps that Gmail lets users send from confirmed e-mail addresses, so she doesn't even need to give out a Gmail e-mail address or send from one. It's totally transparent to the receiver.


Until Hotmail is more interested in providing a transparent service to its users such that the person they're communicating with can't distinguish which e-mail service they're using without going into e-mail headers, then it will never be "professional" to me. And any business that uses a Hotmail e-mail address (or any recognizably free e-mail address for that matter, including Gmail) loses tremendous amounts of credibility points with me. Note: not that they use a free e-mail platform, but that they can't even be bothered to spend <$10/year for a domain and set-up e-mail forwarding & send from options.


At least I don't have to put up with those stupid taglines at all anymore from Hotmail users. Does Yahoo! still put ads on all of its e-mails?


mike fuljenz mike fuljenz mike fuljenz internet marketing course

Automotive Internet Sales Ninjas, Dealer Synergy by dealersynergy


Friday, July 9, 2010

foreclosure investing


Across the United States, newspaper headlines lead with stories about
financial reform. Members of Congress want to better regulate Wall
Street and to take on the fat cats at the big banks, with their golden
parachutes and big bonuses, who took our hard-earned tax dollars in
the form of a federal bailout, despite the fact that they got us in to
this mess in the first place. And Congress is right to take on the
big banks - reform at the national level is long overdue and obviously
needed. But in the hubbub that is the national overhaul, the seeds of
this reform, the work done at the state and local level, cannot be
overlooked nor can we let up on this work. True reform of our banking
and financial systems will take pressure and action at every level and
across the nation.


Americans are fed up with billionaires who are bilking us for all we
are worth, making the middle class the biggest losers. Our friends
and neighbors have lost their homes, found out that the pensions or
retirement savings they worked for are gone and are struggling to find
work in the worst economy of our lifetimes. In the meantime, Wall
Street is back to business as usual, posting new profits, while those
on the other side of the deals have lost their homes, their jobs, and
their retirement savings.


With all of the anger and distrust of Wall Street, we have hit a place
where we are ready for a basic cultural shift - one that turns away
from looking at our investments and banking solely on the basis of
short-term profits, and toward the production of true long-term
growth: by investing our funds in economic growth opportunities that
directly impact our communities.


We cannot let this historic opportunity pass us by. We must channel
our inner Howard Beale and scream from our windows, "I'm
mad as Hell, and I'm not going to take it anymore" - our outrage must
be heard, not just in words but in action.


At the City level, leveraging this cultural shift means investing our
money in banks that are helping grow Main Street by offering small
business loans, working with homeowners to renegotiate mortgages when
they're faced with foreclosure, and opening up bank branches and the
cycle of credit in under-served areas, by creating local versions of
the Community Reinvestment Act standards. After all, what good does
it do Los Angeles if the banks in which the bulk of our tax dollars
sit in are reinvested in another City, far away?


That's why the Los Angeles City Council unanimously supported my proposal to create Responsible Banking Standards in Los Angeles,
based on a Philadelphia model put in place in 2002. Los Angeles alone
has a cash and pension portfolio of over twenty-five billion dollars,
which allows us to leverage these investments in such a way to benefit
the residents of our city - not just through the rate of return, but
by looking at how the banks and financial institutions reinvest in our
community. The ordinance will require that any bank looking to do
business with Los Angeles would have to submit a report to the City
Treasurer who, in turn, would grade the banks based on their
investments in Los Angeles.


And we're not the only ones - cities including Boston, Carson,
Charlotte, Dallas, Denver, Independence, Muskegon and Watsonville are
all looking into creating similar standards for Responsible Banking.
And this week, Boston City Councilor Felix Arroyo is hosting a
Council hearing to examine how the Boston City Council can hold big
banks accountable in their city. The States of California,
Massachusetts, Minnesota, New Mexico, Ohio and Washington are also all
considering or have implemented sweeping financial reforms, including
looking at the creation of State-run banks or investing only in
State-chartered banks.


The anger is palatable and the time for reform is now.


We've lost our trust in the banks that took our bailout money, and let
hundreds of thousands of homes fall into foreclosure.


We've lost our trust in Wall Street, where companies gained enormous
profits, betting on the demise of investments.


We've lost trust in the rating agencies, when 93% of the
subprime-mortgage-backed securities issued in 2006 for which they gave
AAA ratings are now "junk" status.


The only way that trust is going to be restored is with sweeping
reform. That's why Congress must pass substantive financial reform,
so that Americans can begin to believe again. But at the same time,
reform - just as powerful - must come from the cities and states.
Collectively, our leverage is enormous. I introduced a resolution at
the National League of
Cities in support of local reform, because I know the power we
could have if we banded together. Local and state officials know the
pain of our constituents, and know the benefit that can be derived
from holding banks and financial institutions more accountable.


The notion that we can create real change is not just pie in the sky.
The City of Philadelphia has had their policy in place since 2002, which has resulted in
increased consumer and small business lending to historically
under-served areas of that city. And on April 16, Massachusetts State
Treasurer Timothy Cahill announced that the State of Massachusetts
will begin divesting $243 million in taxpayer dollars from three of
the nation's largest banks - Bank of America, Citibank, and Wells
Fargo. The decision came after the banks were asked, and refused, to
voluntarily comply with an 18% interest rate cap on credit cards and
other consumer borrowing for Massachusetts residents. The cap, which
is required of all Massachusetts state-chartered banks, does not apply
to federally-chartered banks.


These actions are just the beginning of our cultural shift. More
Cities and states are needed to create real pressure on the banks. I
urge every City to create standards for how tax-payer dollars are
invested and find ways to ensure that the dollars are going to banks
and financial institutions that are behaving well.


Shouting may not get what we want - but you can bet that billions and
billions of dollars taken elsewhere will get banks' attention.


We are mad as Hell - and we don't have to take it any more.


Hard to say who the worst member of Congress is. But there are few short lists that would exclude narrow-minded and extremist Minnesota religious fanatic Michele Bachmann. However, today isn't about Bachmann. You want Bachmann, you go to DumpBachmann; no one does it better. At the time of the 2008 election, Bachmann was just as odious as she is today. Blue America didn't get involved in that race though because her opponent simply seemed... "better than Bachmann." That standard is too low for us.


And today we're going to meet state Senator Tarryl Clark (below in the comments section), a hard working leader with a proven track record who would be a great candidate whether she were running against Michele Bachmann, or just some garden variety Republican.


People say this suburban/exurban district mostly north of the Twin Cities is too red for a Democrat. But that isn't true. Bush won it in 2004 with 57% and 4 years later McCain took 53% but, the district has also voted to elect Amy Klobuchar to the Senate-- and against Mark Kennedy, the kook who represented the district before Bachmann. And in the 15th senatorial district near St Cloud, the part Tarryl represents-- and which was a GOP bastion before she came along-- the vote totals in that 2006 race were very interesting. Because she knows what it means to work hard and work smart, and with a very committed Wellstone-style of campaigning, Tarryl outpolled everyone on the ballot:


Clark 15581 (56.30%)

Klobuchar 14980 (53.45%)

Pawlenty 14307 (51.1%)

Wetterling 13082 (46.81%)

Bachmann 12542 (44.88%)


MN-06 has the most devastating unemployment rate in Minnesota and the worst foreclosure crisis in the state. But Bachmann has neither understood nor been sympathetic to her constituents finding themselves in a jam because of the vicissitudes of an economy buffeted by disastrous conservative ideological experimentation. She has not only not contributed to finding solutions to these very real problems, she has tried to capitalize of politicizing them.


Tarryl's reaction, as a state legislator, has been the exact opposite. Instead of running around the country and ranting and raving at tea parties, she proven herself an effective leader for the people she represents, working to secure the funds to upgrade the facilities at Saint Cloud State University, working to ensure Central Minnesota’s nursing homes are paid fairly, working to establish a special law enforcement unit to fight gang activities in Central Minnesota.


Tarryl’s been a champion for issues including early childhood and higher education, health care, serving veterans, protecting Minnesotans from predatory lenders, and investing in the local communities that make America strong. Because of that her colleagues elected her to serve as the Senate’s Assistant Majority Leader. Bachmann's colleagues have recognized her as a clown and have tasked her with going on Fox to stir up divisiveness and animosities.


Tarryl’s record of results on reducing unemployment:


• Created 22,000 jobs with last session’s bonding bill


• Helped small businesses add new jobs with Angel Investor Tax Credits


• Authored the Central Minnesota Bioscience Initiative to bring jobs in the biotech industry into the 6th district


• Authored economic development bill that improved workforce development (job training) and expanded the Small Business Growth Acceleration Program, and entrepreneur and small business development grants.


Tarryl’s record of results on reducing foreclosure:


• Authored legislation to protect seniors from predatory lenders and reverse mortgages


• Helped families in keep their homes with the MN Subprime Borrowers Relief Act


• Authored legislation to reduce the burden of property taxes on middle class families


Tarryl is the newest member of the Blue America family. If you can volunteer for her campaign, there's a sign up form here and if you can help the campaign financially, she's on the Blue America endorsed candidates list.


Mike Fuljenz Mike Fuljenz

Investing with Perspective by mwinvesting


Friday, July 2, 2010

foreclosure auctions

Foreclosure Activity by Type

A total of 96,462 U.S. properties received default notices (NOD, LIS) in May, a 7 percent decrease from the previous month and a 22 percent decrease from May 2009. It was the fewest default notices since November 2008 and down 32 percent from the peak of 142,064 default notices in April 2009.

Foreclosure auctions (NTS, NFS) were scheduled for the first time on a total of 132,681 U.S. properties, a decrease of 4 percent from the previous month and down less than 1 percent from May 2009. The May 2010 total was down 16 percent from the peak of 158,105 scheduled auctions in March 2010.

Bank repossessions (REOs) hit a record monthly high for the second month in a row in May, with a total of 93,777 U.S. properties repossessed by lenders during the month — an increase of 1 percent from the previous month and an increase of 44 percent from May 2009. All 50 states posted year-over-year increases in REO activity.

Nevada, Arizona, Florida post top state foreclosure rates in May
With one in every 79 housing units receiving a foreclosure filing in May, Nevada continued to document the nation’s highest foreclosure rate despite a nearly 12 percent decrease in foreclosure activity from the previous month and a 16 percent decrease from May 2009. The state’s foreclosure rate was more than five times the national average.

Arizona foreclosure activity increased less than 1 percent from the previous month and was down nearly 5 percent from May 2009, but the state posted the nation’s second highest foreclosure rate for the second month in a row. One in every 169 Arizona properties received a foreclosure notice during the month — more than twice the national average.

One in every 174 Florida properties received a foreclosure notice in May, the nation’s third highest foreclosure rate, and one in every 186 California properties received a foreclosure notice in May, the fourth highest state foreclosure rate.

Foreclosure activity in Michigan increased nearly 6 percent from the previous month and was up 46 percent from May 2009, helping the state post the nation’s fifth highest foreclosure rate — one in every 223 Michigan properties received a foreclosure filing in May.

Other states with foreclosure rates ranking among the top 10 in May were Georgia, Idaho, Illinois, Utah and Maryland.

Metro foreclosure hot spots continue to post annual declines
With a 1 percent increase in foreclosure activity from May 2009, Vallejo-Fairfield, Calif., was the only metro area with a top-10 foreclosure rate to post an annual increase in foreclosure activity. One in every 101 Vallejo-Fairfield properties received a foreclosure notice in May, the fourth highest foreclosure rate among metropolitan areas with a population of 200,000 or more.

All other metro foreclosure rates in the top 10 were in cities with declining foreclosure activity on a year-over-year basis: No. 1 Las Vegas was down nearly 18 percent; No. 2 Merced, Calif. Was down 7 percent; No. 3 Modesto, Calif., was down nearly 28 percent; No. 5 Cape Coral-Fort Myers, Fla., was down nearly 19 percent; No. 6 Stockton, Calif., was down 33 percent; No. 7 Riverside-San Bernardino-Ontario, Calif., was down nearly 29 percent; No. 8 Bakersfield, Calif., was down 19 percent; No. 9 Reno-Sparks, Nev., was down nearly 18 percent; and No. 10 Phoenix was down nearly 9 percent.


"That's a very good thing," said Thomas Lawler, an independent housing economist in Virginia. But he noted that even with that positive trend, "you are highly likely to see an acceleration in the number of actual completed foreclosures."


Lenders are offering to help some homeowners modify their loans. But many borrowers can't qualify or they are falling back into default. The Obama administration's $75 billion foreclosure prevention effort has made only a small dent in the problem.


About 25 percent of the 1.2 million homeowners who started the program over the past year had received permanent loan modifications as of April. About 23 percent of those enrolled dropped out during a trial phase that lasts at least three months. Many more are in limbo.


Among states, Nevada posted the highest foreclosure rate in May. One in every 79 households there received a foreclosure notice. However, foreclosures there are down 16 percent from a year earlier.


Arizona, Florida, California and Michigan were next among states with the highest foreclosure rates. Rounding out the top 10 were Georgia, Idaho, Illinois, Utah and Maryland.


Las Vegas continued to be the city with the nation's highest foreclosure rate, but activity there was down 18 percent from a year earlier. And nine out of the top 10 cities with the highest foreclosure rates posted annual declines. The exception was the Vallejo-Fairfield area in California, where foreclosures were up 1 percent from a year ago.


Foreclosed homes are typically sold at steep discounts, lowering the value of surrounding properties. That's a concern for local communities, and a drag on the economic recovery.


In recent months, home prices have started to sink again after stabilizing last summer. Economists at Goldman Sachs predicted in a report last week that prices will fall about 3 percent nationally over the next year, with the largest declines in cities where mortgage defaults are rising.


"The housing market remains plagued by enormous excess supply," wrote Goldman economist Sven Jari Stehn.


Get HuffPost Business On
Twitter, Facebook, and Google Buzz!


natural penis enlargement

Foreclosure Rates by Current News Stories

Monday, June 21, 2010

managing your personal finance

Suaad Sait is co-founder of Workstreamer, a business listening platform that delivers actionable, real-time information to business professionals.

As businesspeople, we now have an unlimited amount of constantly updating information at our fingertips. It holds the promise of great value (and more importantly, profit), but it is also voluminous and fleeting.  Powerful new search engines, newfangled social CRM systems, and a preponderance of social sites and services leave us sitting at desks, feverishly fetching news and updates throughout the day in an attempt to stay up-to-date.

The trick, of course, is making sense of all that data, and putting it in context of what companies — and who exactly at those companies — matter most. Increasingly, we have the palpable desire to turn good data into good decisions and profitable relationships. But how can you take advantage of that tsunami of information without risking death by data? How can everyday businesspeople get value out of these data-heavy services and sources? 

Relationships Still Rule

The answer to these questions starts by first acknowledging that it’s the same as it ever was: Business is still all about relationships.  This should be soothing to many for whom the data web is a brave new world. 

The business world still runs on relationships, and data is as much at home at a cocktail hour or on a conference call as it is in a slide deck. The game has not changed much at all. The difference is that today’s business data has put everything in stark relief, at very high resolution. Opportunities and risks have been amplified.

For example, if I notice a partner’s company’s stock surge at the opening of the market and tie it to a news item on quarterly earnings, I can now send a timely congratulatory note and schedule a follow-up meeting to discuss leveraging that momentum for a proposed joint venture.

Or, say I am alerted to an old college friend changing his contact info on a social network, and as a result, track down a few details on his role at a new company. I might subsequently notice via a status update that he is departing for my home city in a few days, and now I can initiate a reconnection and invite him to participate on a panel I’m organizing.

Today’s most actionable business data comes from living and very human sources like social networks, wikis, microblogs, crowdsourced contact directories, collaboratively filtered finance communities, real-time search engines, hyperlocal news sites and more. Managing that data can involve a lot of mixing and matching, comparing and contrasting.

Relationships Run on Data

Strategic relationships with colleagues and contacts both create and consume data. In fact, data isn’t cold and impersonal at all — that’s an important misconception to put to rest. Many of your most successful and trusted business relationships now likely run on data.

“Networking” in the traditional sense used to take a lot of time and effort.  But in truth, all networking has ever been is the act of information-gathering — of scouting and collating.  We used to start with an idea of a person we were trying to do business with, without nearly enough relevant information about them. That has changed as a result of the personal data now available via social media sources.

Now, when you finally meet someone in person, or run into them at a conference, the interaction can be immediately more rich and productive precisely because of data — you can get right to the heart of the matter because you’re having a more informed, in-depth conversation that matters.

From crunching data and doing your homework, to finding a path through your existing relationships, to setting up that first meeting with a timely and well-researched missive, the new data-driven way of doing business can be infinitely more productive.

Conclusion

Remember the under-the-table note sharing going on in high school? 

Well, imagine having the smartest kid in school organize, prioritize and collect notes for you, no strings attached. That’s the kind of information advantage that is now available to us, through an ever-growing array of new social business tools. And it’s not considered cheating, either.

But even despite all this new data and these new tools, relationships are still the beginning and the end of every business decision. 

There is little doubt that there will be a fundamental overhaul in the skill-set of the average businessperson in the next five years as companies grapple with, and realize the upside of making better use of data, both internally and externally.

Today, the technologies and techniques that were once the exclusive domain of Wall Street analysts and Silicon Valley engineers are finally trickling down to everyday businesspeople.   But no matter how the world has changed, listening is still paramount -– listening to customers, listening to prospects, listening to colleagues, and listening to entire companies –- indeed, listening to data.

/>

For more business coverage, follow Mashable Business on Twitterclass="blippr-nobr">Twitter or become a fan on Facebookclass="blippr-nobr">Facebook

/>

More business resources from Mashable:

- How Data Will Impact the Way We Do Business/> - HOW TO: Make Sure You’re Tracking the Right Data/> - 4 Tips for B2B Marketing on Facebook/> - What Facebook’s Open Graph Means for Your Business/> - HOW TO: Cultivate Your Brand’s Super Users

Image courtesy of iStockphotoclass="blippr-nobr">iStockphoto, Sportstock, stevecoleccs


Mint.com helps Web users who are willing to enter their bank and credit card account information track their spending and savings. Now another start-up called Wikinvest wants to do the same thing for investments.


Wikinvest, as we have written about, is a site with user-generated information about stocks — Wikipedia meets Yahoo Finance. On Wednesday, it will introduce a tool that imports information from a user’s brokerage and investment accounts and arranges it in a readable way.


“Today, lots of people are paying more attention to the markets, but there is no good way to do this,” said Michael Sha, a co-founder of Wikinvest.


Some people enter the data manually in spreadsheets. Others track their personal investments on sites like Yahoo Finance and Google Finance, but few do so, Mr. Sha said, because it requires entering each investment manually.


Brokerage Web sites track investments, but many people have several accounts, and these sites rarely include information like news reports.


Wikinvest will sync with 25 brokerages, including Scottrade, Charles Schwab and Vanguard. Users enter their brokerage account log-ins on Wikinvest, and Wikinvest will import their investment information and present it in easy-to-read columns that show things like the 52-week price range for stocks and recent news headlines and Wikinvest articles that could affect investments.


Charts compile all a user’s investments, across brokerage accounts, taking into account information like deposits and withdrawals, dividends and fees, and compare performance to the rest of the market.


This could be useful for people managing their own money or for people who want to monitor what a financial planner is doing with their money, Mr. Sha said.


Having the information compiled in one place could also be useful when tax season comes around — Wikinvest could automatically fill in Schedule D forms, he said.


In the next few weeks, Wikinvest will add personalized, real-time e-mail alerts about news related to stocks that an individual owns. The company is also building versions for the iPhone and iPad.


The service is free, and eventually Wikinvest plans to make money off of it by running various types of ads.


These could include suggesting an index fund similar to one that somebody owns but with a lower fee, or suggesting investments catered to someone’s risk level, asset level and interests. Wikinvest could also refer users to accountants, brokers or financial planners.


“The relevance of having your portfolio data with alerts is even more relevant when it comes to making decisions,” Mr. Sha said. “We can target better ads.”


This is also like Mint, which makes money by suggesting credit card or bank accounts with lower fees, for example, and then earning an affiliate fee when users sign up.


Many people might be hesitant about entering their brokerage log-ins and passwords on Wikinvest.


“Hopefully the value we can provide as a result is worthwhile,” Mr. Sha said, raising an issue that was also addressed in a recent Times article. “A lot of work was done by Mint to pave the way in getting people comfortable.”


The site has taken pains to secure its hardware and encrypt its Web site, said Mr. Sha, who previously worked on fraud prevention at Amazon.com.


Even if an intruder broke into the Wikinvest site and could see a user’s balances, it is impossible to trade or access brokerage accounts from the site.


penis enlargement


If you're reading this article, you have more of an interest in taking control of your financial situation than most. In reality, many people don't actively seek out information about how to effectively manage their money or even maintain the family budget. Instead, you'll see a lot of people rely on tips from a broker, friend, or brother who may not have put any research into their own decisions themselves. When it comes to something as important as their own financial well-being, people for some reason seem remarkably disinterested in becoming educated in things like how to properly save for college, what to do to secure a comfortable retirement, or even how to manage the monthly bills.

But you are reading this article which means you are interested. In that case, let's take a look at some of the best resources out there for financial education and money management.

If you're saving for college, go to www.savingforcollege.com - There are many options out there for saving for Junior's college bills. This is a great site for learning not only about 529s and Coverdell Education Savings Accounts (a lesser known option in addition to the 529) but also for help in figuring out how much you should save, applying for financial aid, tax consequences, and getting in contact with a financial professional.

If you're saving for retirement, go to www.401k.com - This site, run by Fidelity (who happens to be one of the retirement plan powerhouses), is the best place to get all the basics. The planning calculators available are particularly enticing as they cover everything from saving to budgeting to the growth of your money. Plus, if you're ready to invest, Fidelity is more than happy to help.

If you're learning about investments, go to www.morningstar.com - If you're a beginner, mutual funds are probably your best bet for dipping your toe in the water and Morningstar is the recognized industry leader in fund analysis. This site has the potential to be a bit overwhelming with the abundance of information available so you may want to stick with the basics before diving in. The Personal Finance section may be the ideal starting point.

If you're learning about the stock market, go to finance.yahoo.com - This site is my personal favorite and I keep it open during the day while at work. It's a great place for learning about and following the stock market and provides regular contributions from a number of financial experts.

If you're managing credit card debt, go to www.annualcreditreport.com - If you can get past the infomercials and catchy jingles, there's only one website that is authorized to provide you a free annual copy of your credit report and that's this one (the others usually require a subscription to a credit monitoring service which costs money). Everybody should have a copy of their credit report in hand to protect against unauthorized activity in your name and potential identity theft. There's probably no better free money saving idea out there than this.

There are a lot of great resources today to guide you in the journey towards financial independence. The biggest challenge is taking that first step. Financial literacy is an ongoing effort that few people ever really master but taking the time to learn will keep you several steps ahead of the pack.


Get Rid of Useless Facebook <b>News</b> Feed Posts – Simple Help

You know all those annoying “apps” that your friends use (FarmVille, Mafia Wars, Gift Creator etc) and end out showing up in your Facebook News Feed? This tutorial will show you how to use F.B Purity to clean up your Facebook News Feed ...

Breaking <b>news</b>: Arizona Diamondbacks recall outfielder Cole <b>...</b>

The former Oregon State and West Linn High School star batted .256 during his first stint with the Diamondbacks earlier this season.

At Buffao <b>News</b>, New Rules for Online Comments - Media Decoder Blog <b>...</b>

In a significant step toward reigning in the largely unpoliced world of anonymous online commenting, The Buffalo News said that it will require all people who leave comments on its website to identify themselves.